
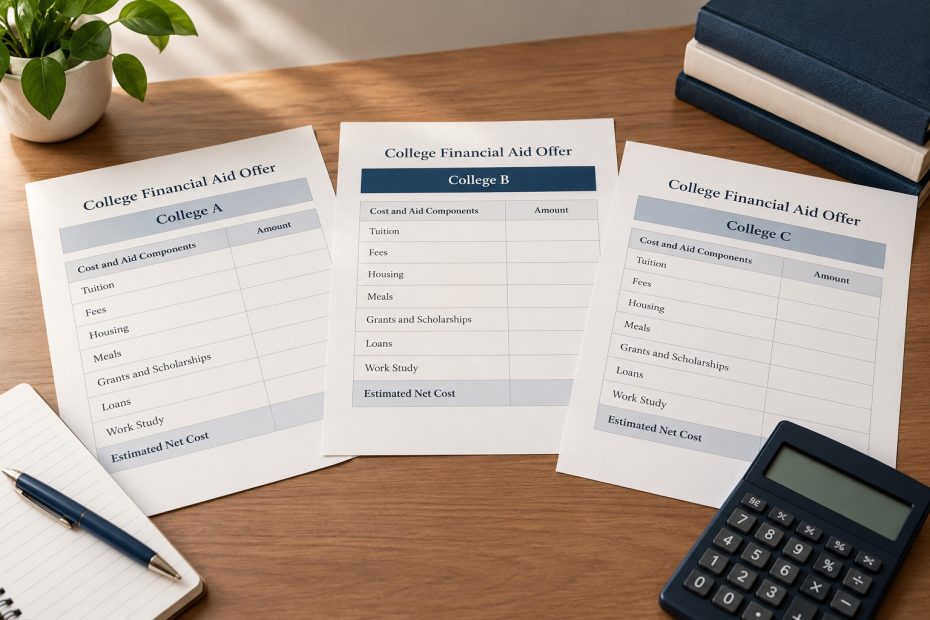
To compare financial aid offers, use matching time periods, document the full costs, and subtract applicable grants and scholarships before considering borrowing. Show loans, possible work earnings, and unresolved funding conditions separately so the comparison doesn’t hide what you would still need to pay.
The three-school worksheet below helps you organize those distinctions and the questions behind them. You will also check renewal terms, payment timing, and the source of each figure before relying on a total.
Make the comparison period match
Write the academic year or term at the top of each offer. Confirm whether its figures cover one semester, a full academic year, or another period. Don’t compare a semester’s tuition with another school’s annual tuition.
Check enrollment assumptions and living arrangements too. An estimate for living with family won’t describe the same expenses as a campus housing plan. Keep the school’s original figures, then label any personal adjustments you make.
Create a separate evidence folder for each school and save the version of the offer you are using. Record whether it is an estimate, an initial offer, or a revised offer. If a new document arrives, update the worksheet from that version and retain the earlier one for comparison. Otherwise, it is easy to combine one school’s old costs with its new funding.
Use the same personal assumptions wherever they genuinely apply. If you plan to study full time at one college and part time at another, keep that difference explicit rather than forcing the two plans into an identical category. Your comparison should show the consequences of the options you are actually considering, including differences in the period each cost covers.
Separate the bill from the full cost
Federal Student Aid’s aid-offer guidance says an offer may not show every cost of attending. Tuition and school-billed charges are only part of your comparison. You may also need books, supplies, transportation, and living expenses paid elsewhere.
Ask each school which costs are included in its published estimate. Add a missing expense only once. If housing already appears in the cost total, adding the same housing estimate again will exaggerate the price.
Build a short cost inventory before calculating the total. Identify tuition and required charges, housing and meals, books and supplies, and travel relevant to your plan. Then mark which items appear on the college account and which you would pay elsewhere. The purpose is to check completeness, not to assume that every student incurs every category.
An amount can be documented and still be an estimate. A published transportation allowance isn’t necessarily your commuting cost, and a school housing estimate may differ from the arrangement you choose. Keep the official estimate visible, add a separately labeled personal planning figure where needed, and record why the figures differ. Don’t silently rewrite the original offer.
Sort each funding line by what it means
Federal Student Aid distinguishes money that generally doesn’t require repayment, borrowed funds, and money you must earn. Grants and scholarships belong in the gift-aid category, subject to their conditions. Loans remain borrowing. Work-study requires obtaining a job and working to receive pay.
Copy the full award name beside its category. If an abbreviation is unclear, ask the school to identify it before including it in your calculation. A work-study offer is not money already available for a bill.
Create a question beside any award you can’t classify confidently. Ask whether it is a grant, a scholarship, borrowing, or an opportunity to earn money, and whether further steps are required before it can be used. Don’t infer the category from an encouraging name or from where the item appears on the page.
For borrowing, note who would be responsible for repayment and which terms still need review. This worksheet doesn’t decide whether a loan is appropriate. It makes the proposed borrowing visible so you can discuss it separately from the price of attendance. Keep a possible loan outside your confirmed resources until you understand its approval and acceptance requirements.
Complete the three-school worksheet
For every amount entered below, include its source and date in the same cell. Use “unknown” for missing information, not zero. The worksheet is a comparison aid, not an official financial-aid calculation.
|
Comparison item |
School A |
School B |
School C |
|
Period and enrollment basis |
______ |
______ |
______ |
|
School-billed costs |
______ |
______ |
______ |
|
Other attendance costs |
______ |
______ |
______ |
|
Total planned costs |
______ |
______ |
______ |
|
Confirmed grants and scholarships |
______ |
______ |
______ |
|
Costs minus gift aid |
______ |
______ |
______ |
|
Student loans offered |
______ |
______ |
______ |
|
Parent or other borrowing proposed |
______ |
______ |
______ |
|
Potential work-study earnings |
______ |
______ |
______ |
|
Renewal conditions and missing answers |
______ |
______ |
______ |
Calculate costs minus gift aid before considering loans. You can then assess possible ways to pay that remaining amount without changing the underlying price. Record outside awards separately until each school explains their treatment.
Treat each cell as a small evidence record. Enter the amount, the period it covers, the document or webpage, and the date checked. If a figure was confirmed during a call, note the office and ask where the information is available in writing. Those details let another person follow your comparison without having to reconstruct your research.
Check the arithmetic in layers. First total the costs that belong to the same period. Then total the applicable grants and scholarships without counting an award twice. Subtract that gift aid from the costs, then show proposed payment sources separately. A loan can help finance a remaining cost, but moving it into the gift-aid row would conceal the repayment obligation.
Ask what continues beyond the first year
For each award, ask whether it is renewable, what conditions apply, and how many terms it can cover. Request the written policy rather than assuming the first offer repeats unchanged.
Also ask what happens after a change in enrollment or living arrangements. You don’t need to predict every possibility. You do need to know which assumptions your current comparison depends on and which office can explain a change.
Turn “renewable” into a set of specific questions. Ask about the number of eligible terms, enrollment requirements, academic conditions, application steps, and when continuation is confirmed. Record the answer for each award rather than assuming all aid at the same school follows one policy. If the policy refers you elsewhere, save the linked document too.
Keep future-year questions separate from the current offer. You can identify uncertainty without inventing a future tuition increase or assuming an award will disappear. Ask the college which costs and funding details are known for later periods and which cannot yet be confirmed. That distinction is more useful than projecting a precise multi-year total from incomplete information.
Compare timing and unresolved gaps
Record bill due dates and the expected availability of confirmed funding. A semester may look funded overall but still require money before an award arrives. Ask student accounts how the school handles pending aid and which charges remain your responsibility during processing.
Keep a question list for each institution. A missing answer about borrowing or renewal is a reason to investigate, not an invitation to enter an optimistic estimate. The scholarship homepage is a separate resource for current program information, not a promise of additional funding.
Ask what must happen before aid appears on the account. If there are outstanding documents or acceptance steps, record them beside the expected funding date. A pending requirement and an unexplained delay are different issues, and the office needs to know which one you are asking about. Keep payment timing questions directed to the office responsible for the bill.
Before choosing, review the questions most likely to change your understanding of an option: an unidentified loan, a missing housing charge, an uncertain award condition, or an early payment requirement. Mark each as answered, pending, or no longer relevant. A worksheet with visible unknowns is more dependable than a complete-looking table built from assumptions.
What should an offer comparison show?
- Matching time periods and enrollment assumptions.
- School-billed and other costs.
- Grants and scholarships separately from loans.
- Work earnings, renewal conditions, and payment dates.
Choose with the unanswered questions visible
Review the completed worksheet with the financial-aid offices and anyone helping you pay. Keep borrowing, uncertain awards, and personal estimates visible. The useful comparison is the one that shows what each option requires from you, including the questions still awaiting an answer.
References
Federal Student Aid: How to evaluate your aid offers

Loral Langemeier is a financial educator, investor, and five-time New York Times bestselling author with 20+ years of experience. A media-featured speaker and co-founder of the Attainable Wealth Association, she helps families and professionals build generational wealth through entrepreneurial income, smart investing, and financial education.